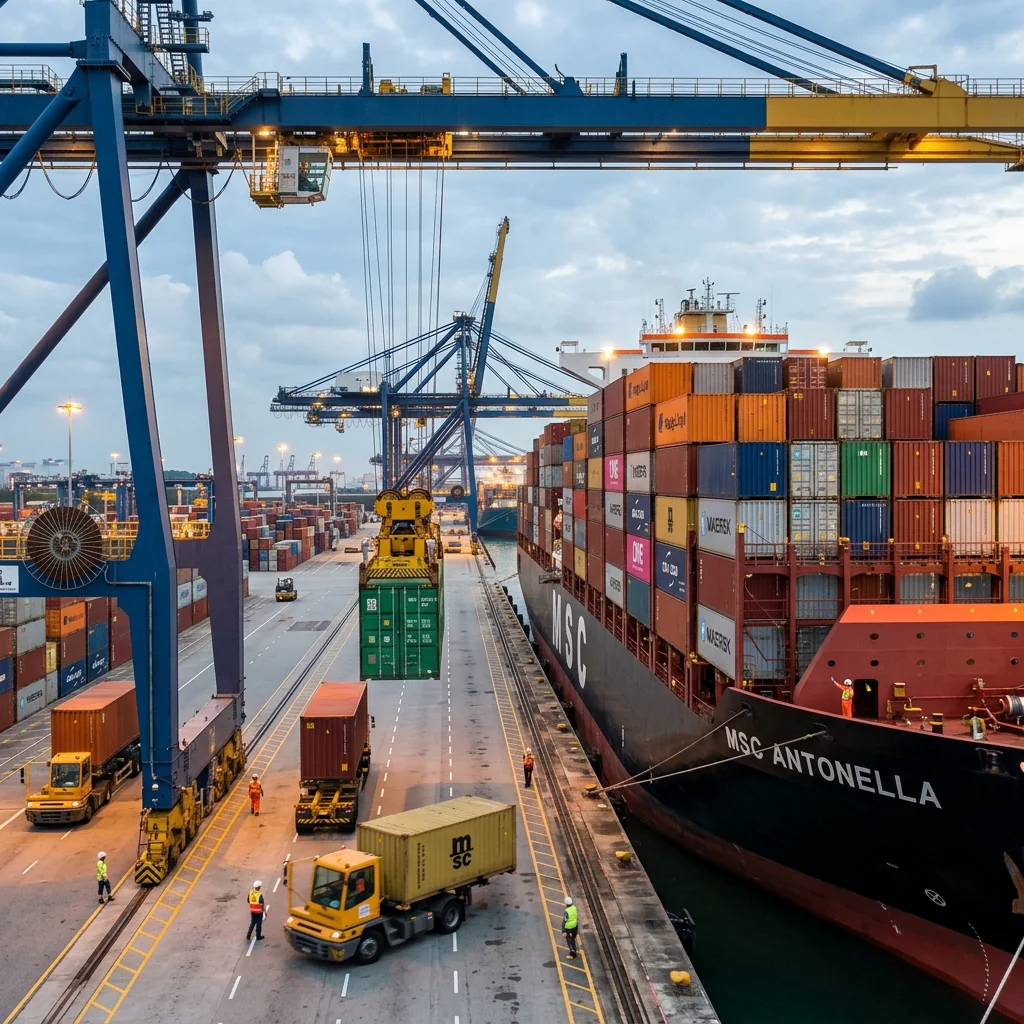
Compare trade terms by the delivery point, risk transfer, transport costs and customs responsibilities. Under CIF, the destination named for paid freight is different from the point where transit risk transfers. Record the named place or port and rules edition in the contract; payment, ownership and remedies also need agreement.
FOB
Free On Board applies to sea or inland-waterway delivery. The seller clears the goods for export and delivers them on board at the agreed shipment port, where transit risk transfers to the buyer. The allocation of particular charges still needs to be checked against the rule and contract.
Request a breakdown of the goods price and the seller's export packing, clearance, transport and loading obligations. State the shipment port and delivery point precisely, with any separately agreed services.
Arrange the onward carriage and any insurance you require, then check import clearance, duties, taxes and final delivery charges. Specify who provides the documents and information needed for those steps.
For containerized cargo handed to a carrier or terminal before vessel loading, consider FCA with a precise delivery point. It better reflects that handover. Use FOB where the agreed delivery is genuinely on board the vessel. The ICC rule-selection checklist distinguishes these cases.
CIF
Cost, Insurance and Freight applies to sea or inland-waterway transport. The seller pays the agreed carriage and arranges cargo insurance to the named destination port, while transit risk transfers on board at the shipment port.
Paid freight to destination does not mean the seller bears transit risk to destination. For a voyage loss, establish the cause, insurance terms and available claims. Risk transfer does not determine every contractual remedy for defective goods or another breach.
Obtain the insurance policy or certificate and check insured parties, claim rights, insured value, route, exclusions and any additional cover needed. Under CIF 2020, the default cover is Institute Cargo Clauses (C) or similar unless otherwise agreed, with an insured amount of at least 110% of the contract price. Check the actual evidence of cover; the amount is not a promise that every loss is insured.
Itemize destination charges before comparing quotations. Unloading charges already payable by the seller under its carriage contract cannot simply be charged again unless otherwise agreed. Import clearance, duties and taxes remain buyer responsibilities under CIF. Do not infer the total from the FOB or CIF label alone; the ICC CIF and CIP explanation describes the transport and delivery distinction.
DDP
Delivered Duty Paid places delivery and import-clearance responsibilities on the seller at the named destination, with the goods on the arriving vehicle ready for unloading. The buyer bears the unloading risk; check whether unloading costs are included in the carriage contract. DDP does not require the seller to purchase cargo insurance for the buyer.
Specify the destination and verify how the seller will lawfully perform the import obligations before relying on a delivered price.
Identify the declarant, authorized customs representative and legally permitted import arrangements for the destination. DDP allocates obligations between buyer and seller; it does not override national customs requirements. If the seller cannot perform import clearance, agree an appropriate alternative such as DAP instead of leaving the stated term inconsistent with the actual arrangement.
Request a documented declaration process covering the true product description, transaction value, origin and classification. State who keeps the entry records and handles customs questions or corrections. Legal liabilities depend on the jurisdiction and actual declaration roles; a price difference alone does not prove undervaluation.
Confirm which entity will appear on the import entry and which evidence is available for any applicable tax-credit claim. Eligibility depends on local rules, registration and documentation. Have the destination customs or tax representative explain the proposed arrangement before treating tax as recoverable.
DDP can be used where the seller can perform its agreed obligations and the import arrangements have been verified. Size alone does not decide suitability. Ask for the relevant entry records and clarify any access limitation; the ICC DDP explanation covers delivery, unloading and import formalities.
The charges quotations leave out
Build an itemized cost comparison: goods, export handling, carriage, insurance if chosen or required, destination handling, clearance, duties, taxes, possible storage and final delivery. Mark each line as included, separately payable or conditional under the proposed arrangement. Obtain current quotations for this cargo and route.
Give the forwarder or customs representative the actual product descriptions, proposed tariff classifications, packed dimensions and weights, route and delivery point. Confirm quote validity, exclusions, minimums and the cost of foreseeable delays.
Choosing
For a container or multimodal shipment, review FCA with a named handover point if you arrange main carriage. If considering EXW, establish who can handle loading and export formalities before accepting the responsibilities.
For on-board sea delivery, compare FOB with a buyer-appointed carriage quotation. Volume does not prove that one party will obtain a better rate: compare the actual transport contract, fees and delivery responsibilities.
CIF can fit sea delivery where the seller arranges freight and the required cover. Check the shipment point, insurance and complete destination charge schedule before agreeing.
Use DDP only with verified import arrangements and a precise delivery point. Discuss DAP or another suitable rule if the agreed customs roles differ. Read the official rules alongside the sales and transport contracts; Trade.gov explains the matters Incoterms leave to the sales contract.
Our scope is sourcing coordination with third-party forwarders; we do not operate freight, customs clearance or DDP services ourselves. Request a trade-quotation scope review with the supplier quote, named delivery point, product and packing details, destination and proposed customs roles. We can identify which costs and responsibilities still need confirmation.